BUSINESS
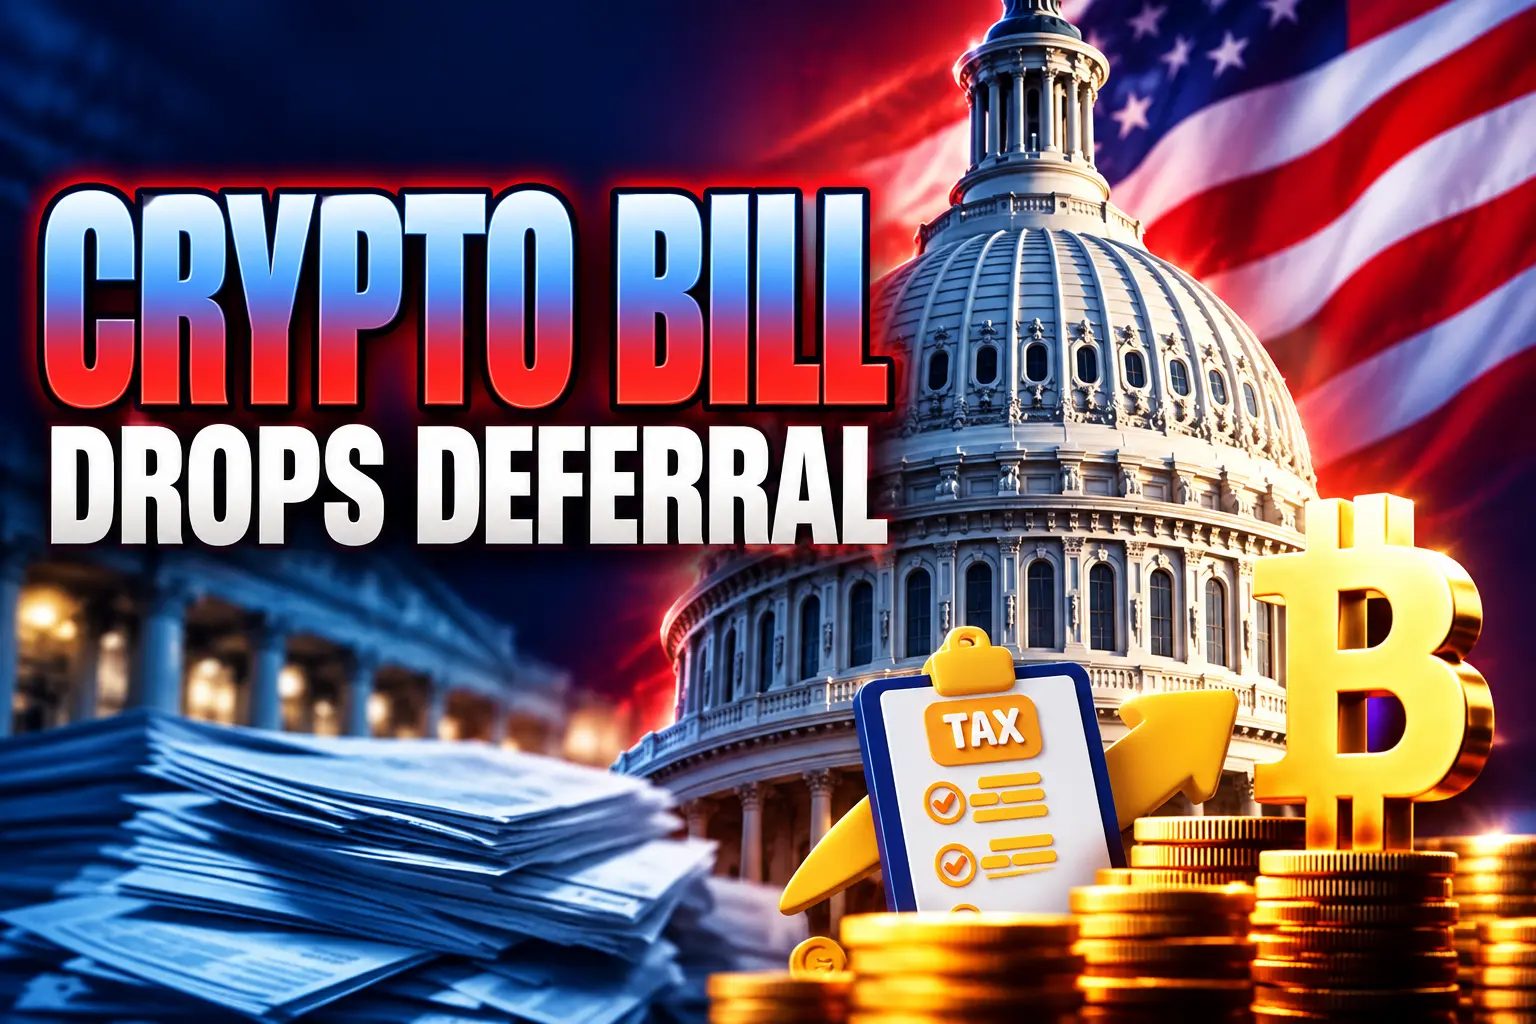
The House Crypto Tax Bill Drops Mining Deferral at Markup
House tax writers mark up a crypto tax bill on Sept. 16 that keeps wash-sale rules and drops mining deferral after a Democratic standoff.

The House Ways and Means Committee will mark up a 114-page crypto tax bill on Sept. 16 after cutting the mining and staking deferral that had blocked Democratic votes. Chairman Jason Smith’s vehicle is H.R. 10357, the Digital Asset Tax Certainty Act, posted late on Sept. 14 and listed for 10:00 a.m. ET in HVC-210.
The title promises certainty. The text that can move is smaller: wash-sale and constructive-sale rules for traded tokens, a $10 break on network fees, and ordinary-income treatment for mining and staking without a delay until sale.
A 114-Page Tax Bill Goes to the Gavel
Smith, a Missouri Republican, folded a summer’s worth of standalone drafts into one chairman’s bill. The committee markup notice for Sept. 16 puts H.R. 10357 first among seven measures, alongside unrelated tax and health bills. A vote in committee would send the crypto title toward the House calendar. It would not change the Internal Revenue Code on its own.
The circulated 114-page Digital Asset Tax Certainty Act runs seven titles. Wash-sale and constructive-sale rules that now cover stock would reach traded digital assets. Dealers and traders would get a mark-to-market election under section 475, and qualifying loans would get nonrecognition treatment that securities lending already enjoys. Charitable gifts of widely traded tokens would get easier appraisal rules. A voluntary disclosure program would be stood up within 12 months. A Puerto Rico sourcing fix sits in the anti-shelter title. Title IV still talks about mining and staking, but only to lock in ordinary-income character and source rules.
WHAT SURVIVED IN H.R. 10357
| Item | In the markup text | What changed from June |
|---|---|---|
| Wash-sale and constructive-sale rules | Yes, for traded digital assets | Folded in from H.R. 9172 |
| Mining and staking deferral election | No | Core of H.R. 9175 dropped |
| Mining and staking income character | Ordinary income, with sourcing rules | Kept in Title IV |
| Network fees of $10 or less | No gain or loss, with a volume limit | Folded in from H.R. 9178 |
| Dollar stablecoin simplification | Yes | Kept in Title I |
| Section 475 mark-to-market and section 1058 lending | Yes | Folded in from the parity drafts |
| Charitable gifts of widely traded tokens | Yes | Folded in from H.R. 9173 |
| Voluntary disclosure program | Yes, within 12 months | Folded in from H.R. 9174 |
| Wagering-loss deduction rider | Yes, unrelated to crypto | Added as Title VII |
The fee break is real and narrow. The bill would ignore gain or loss on a network fee of $10 or less, then pull that relief away from anyone who made more than 5,000 transfers in the prior year. Paying a small gas fee would stop generating a tax lot. Running a high-volume wallet would not.
The Deferral That Bought Democratic Votes Got Cut
Rep. Mike Carey, an Ohio Republican, introduced the Tax Clarity for Mining and Staking Act on June 8 as H.R. 9175. That draft kept the IRS view that newly minted rewards are ordinary income, then offered an election to wait until sale. Miners and validators would still owe tax. They would not owe it on coins they had not turned into cash.
Rep. Steven Horsford, a Nevada Democrat who co-authored the broader Digital Asset PARITY Act with Rep. Max Miller of Ohio, treated unlimited deferral as a problem. Ahead of the June 9 hearing he filed an amendment that would have capped the delay at five years. Crypto Council for Innovation chief executive Ji Hun Kim said that clock would wreck the bill.
Rep. Horsford’s amendment would unfortunately break H.R. 9175, replacing it with a 5-year forced-sale clock on staking and mining rewards that JCT says raises negligible revenue.
Ji Hun Kim, CEO, Crypto Council for Innovation
The Blockchain Association, the Crypto Council for Innovation, and The Digital Chamber made the same ask in a June 21 letter to Smith and Ranking Member Richard Neal: pass Carey’s bill without that cap. Banks had already argued that a special delay for crypto yield would sit poorly next to dividends and interest. Democrats on the committee said a crypto-only deferral looked like a privilege.
HOW THE DEFERRAL FELL OUT
- June 8, 2026: Carey introduces H.R. 9175 with an optional delay until sale; Rep. Jodey Arrington of Texas introduces H.R. 9172 on wash sales. Horsford files a five-year cap.
- June 9, 2026: Ways and Means holds a full-committee hearing on the digital-asset tax drafts.
- June 21, 2026: Three crypto trade groups ask Smith to keep unlimited deferral.
- Sept. 13, 2026: Republicans weigh stripping the mining and staking timing rules to keep Horsford on the package.
- Sept. 14, 2026: Smith introduces H.R. 10357. Title IV sets character and source as ordinary income and leaves the deferral election out.
- Sept. 16, 2026: The combined bill is set for markup at 10:00 a.m. ET.
Horsford, the holdout on timing, has said he supports the latest text and that it will get bipartisan sign-off. That is the bargain. Industry groups spent the summer defending a delay until sale. The chairman’s bill keeps the tax on receipt and drops the delay, which is a harder outcome than Horsford’s five-year cap.
Wash-Sale Rules Would End Same-Week Loss Harvests
Sell a share of stock at a loss on Monday and buy it back on Tuesday, and section 1091 already disallows the loss. Sell Bitcoin the same way and the Code still treats the token as property, not as stock or securities, so the loss can stand. Arrington’s June draft, now inside H.R. 10357, would close that gap for actively traded digital assets and related contracts, with carve-outs aimed at qualified dollar stablecoins and some validation rewards.
The mechanics are familiar. A wash sale is a sale at a loss plus a purchase of a substantially identical asset in the 30 days before or after. The disallowed loss is not erased forever; it is added to the basis of the replacement lot. Constructive-sale rules would also reach digital assets other than qualified dollar stablecoins, so a holder who locks in a gain with an offsetting position could be treated as if a sale had occurred.
That is the part of “certainty” that raises money. The Joint Committee on Taxation, scoring the June standalone wash-sale bill rather than Smith’s later combined text, estimated H.R. 9172 would raise $2.074 billion over fiscal years 2026 through 2036. The same JCT pamphlet scored Carey’s deferral draft as a $2.956 billion revenue loss over that window. Cutting the deferral and keeping wash sales flips the package from a net tax cut for validators toward a net tax increase for traders who harvest losses and jump back in.
JUNE JCT SCORES ON THE STANDALONE DRAFTS
- Wash-sale bill (H.R. 9172): Joint Committee on Taxation estimated a $2.074 billion revenue increase over fiscal years 2026 through 2036.
- Mining and staking deferral (H.R. 9175): The same scorekeepers estimated a $2.956 billion revenue loss over that window.
- Markup vehicle (H.R. 10357): No separate JCT table has been issued for the combined Sept. 14 text, which keeps wash sales and drops the deferral election.
The Bipartisan Policy Center has laid out how mining, staking, and wash sales should be taxed as a fairness and revenue question, not only an industry wish list. Extending the 30-day rule puts tokens next to stocks. It also hits the December habit of selling losers, booking the loss, and buying the same coins back before the year turns. Brokers already face digital-asset proceeds reporting for sales on or after Jan. 1, 2025, and basis reporting for certain sales on or after Jan. 1, 2026, under the July 2024 Treasury regulations. A wash-sale overlay would land on that reporting stack.
What Miners and Stakers Still Owe the IRS
Current law did not wait for Carey’s bill. Notice 2014-21 told miners to include the fair market value of coins as income when they receive them. A 2023 revenue ruling reached the same timing for staking once the taxpayer has dominion and control, meaning the ability to sell or otherwise dispose of the reward. The Tax Court has also treated staking rewards as income on receipt. H.R. 10357 would write ordinary-income character and sourcing into statute and stop there.
That leaves the cash-flow bind the deferral was written to ease. A validator can owe tax on tokens that have no ready buyer, or that fall in price after the income is booked. Basis goes up by the amount included, so a later sale is not taxed twice on the same dollars, but the first bill still comes due in the year of receipt. Title IV’s sourcing rules would generally follow U.S. residence at acquisition or disposition, a quieter fight than timing and one aimed at offshore structures.
CURRENT IRS TIMING, BEFORE ANY NEW STATUTE
- Mining: Fair market value is included as ordinary income on receipt, per Notice 2014-21.
- Staking: Fair market value is included when the taxpayer has dominion and control, per the 2023 revenue ruling.
- Property, not currency: Convertible virtual currency is treated as property, which is why wash-sale rules written for stock have not clearly applied.
- Where to look: The IRS frequently asked questions on digital assets still walk through those property rules for people who file now.
Investment-trust staking language remains in the combined bill, a narrower fix for funds that accept rewards and worry about their tax status. That is useful for some products. It is not a delay until sale for a home validator.
Same Morning, a Strategic Bitcoin Reserve Vote
Ways and Means is not the only House panel with crypto on the clock. The Financial Services Committee has listed a Sept. 16 markup of various measures for 10:00 a.m. in 2128 Rayburn, and H.R. 8957, the American Reserve Modernization Act of 2026, is on that slate. Rep. Nick Begich, an Alaska Republican, introduced the bill on May 21 with Democratic co-sponsor Rep. Jared Golden of Maine and more than 20 cosponsors.
ARMA would tell Treasury to stand up a Strategic Bitcoin Reserve within 180 days, impose a 20-year lockup on bitcoin in that reserve, and require quarterly third-party proof-of-reserve reports. Non-bitcoin tokens would sit in a separate Digital Asset Stockpile. The political contrast is blunt. One committee is writing tax rules that reach household wallets. The other is writing a statute around coins the government already holds.
THE HOUSE CRYPTO SLATE ON SEPT. 16
- Ways and Means, 10:00 a.m. ET, HVC-210: Markup of H.R. 10357 and six other bills.
- Financial Services, 10:00 a.m. ET, 2128 Rayburn: Markup slate that includes H.R. 8957, the American Reserve Modernization Act.
- Senate, Sept. 15, 2:15 p.m. ET: Cloture on the motion to proceed to H.R. 3633, the CLARITY market-structure bill, needing 60 votes.
CLARITY is the louder fight. Senate sponsors Cynthia Lummis, John Boozman, and Tim Scott released a substitute they called their last offer, counting 126 changes Democrats had asked for, including ethics limits on officials and their spouses. Republicans hold 53 seats, so seven Democrats or independents would have to join a united GOP conference to hit 60. Democrats circulated a further counterproposal as that procedural vote approached. None of that rewrites the tax code. It does suck oxygen from a tax markup that actually tells people what to put on a return.
Recess Comes Before Any House Floor Fight
Committee passage is the first vote, not the last. The House is scheduled to break until after the November election, which leaves little room to bring a tax title to the floor, reconcile it with the Senate, and put a signed change into the 2026 filing season. A markup can still lock in text, force amendments into the open, and give both parties a recorded position to carry into 2027.
The irony sits in that sequence. Smith’s bill uses “certainty” in the title, and several titles do reduce paperwork: small network fees, stablecoin lots, charity appraisals, a path to come forward on old returns. The fight that defined the summer, when miners and stakers pay, is the piece that came out so Horsford could come in. What remains for traders is the rule stock investors already live with, the 30-day wash-sale window, scored in June as a multi-billion-dollar raiser.
If the committee reports H.R. 10357 on Sept. 16, the House will have a crypto tax bill on paper. Miners will still owe tax when rewards hit the wallet. Traders who sell losers and buy them back in the same month will be on notice that the old gap is the price of a deal that could actually leave the room.
Disclaimer: This article is news reporting and analysis of pending U.S. tax legislation. It is informational only and is not tax, investment, or legal advice, and it does not tell any reader how to file, trade, mine, stake, or hold digital assets. Tax results depend on facts, timing, and the final statutory text, which can change in committee, on the floor, or in a later Congress. Readers should consult a qualified tax professional or enrolled agent before acting on any provision discussed here. Bill numbers, scores, and committee schedules reflect the public notices and drafts available on Sept. 15, 2026, and may change.

Russia Makes Factory Owners Buy Air Defense They Cannot Run

Trump’s Fed Chair Prepares a Hike as Yields Top 5%

Saudi Red Line at Mecca Meets a Pact Still Forming

Meta Builds Camera-Free Glasses for Rooms That Ban Recording

Depotcharge Turns Idle Truck Chargers Into a Haulier Club

Sons of Behemat Add a Witch and a Middle Rank

Canada Still Clears Mazatlán as the Cartel War Arrives

The FTC Suit That Targets Amazon’s Hidden Ad Floor

Apple’s Foldable iPhone Event Revives the Fingerprint Button

The Unstoppable Rise of Hot Honey: Are Food Trends Making UK Restaurant Menus All the Same?
-
 GAMING4 weeks ago
Sons of Behemat Add a Witch and a Middle Rank
-
 NEWS2 years ago
Canada Still Clears Mazatlán as the Cartel War Arrives
-
 BUSINESS1 month ago
The FTC Suit That Targets Amazon’s Hidden Ad Floor
-
 NEWS1 month ago
Apple’s Foldable iPhone Event Revives the Fingerprint Button
-
 LIFESTYLE2 years ago
The Unstoppable Rise of Hot Honey: Are Food Trends Making UK Restaurant Menus All the Same?
-

 LIFESTYLE2 years ago
Women, Gym, and Affairs: A Complex Intersection
-

 NEWS3 weeks ago
Samsung Leads Mistral’s Record European Sovereignty Round
-

 ENTERTAINMENT2 years ago
SetonFest Grew From a 1981 Picnic Into Carmel’s Carnival