BUSINESS
Treasury Yields Hit a 24-Year High as AI Joins the Queue
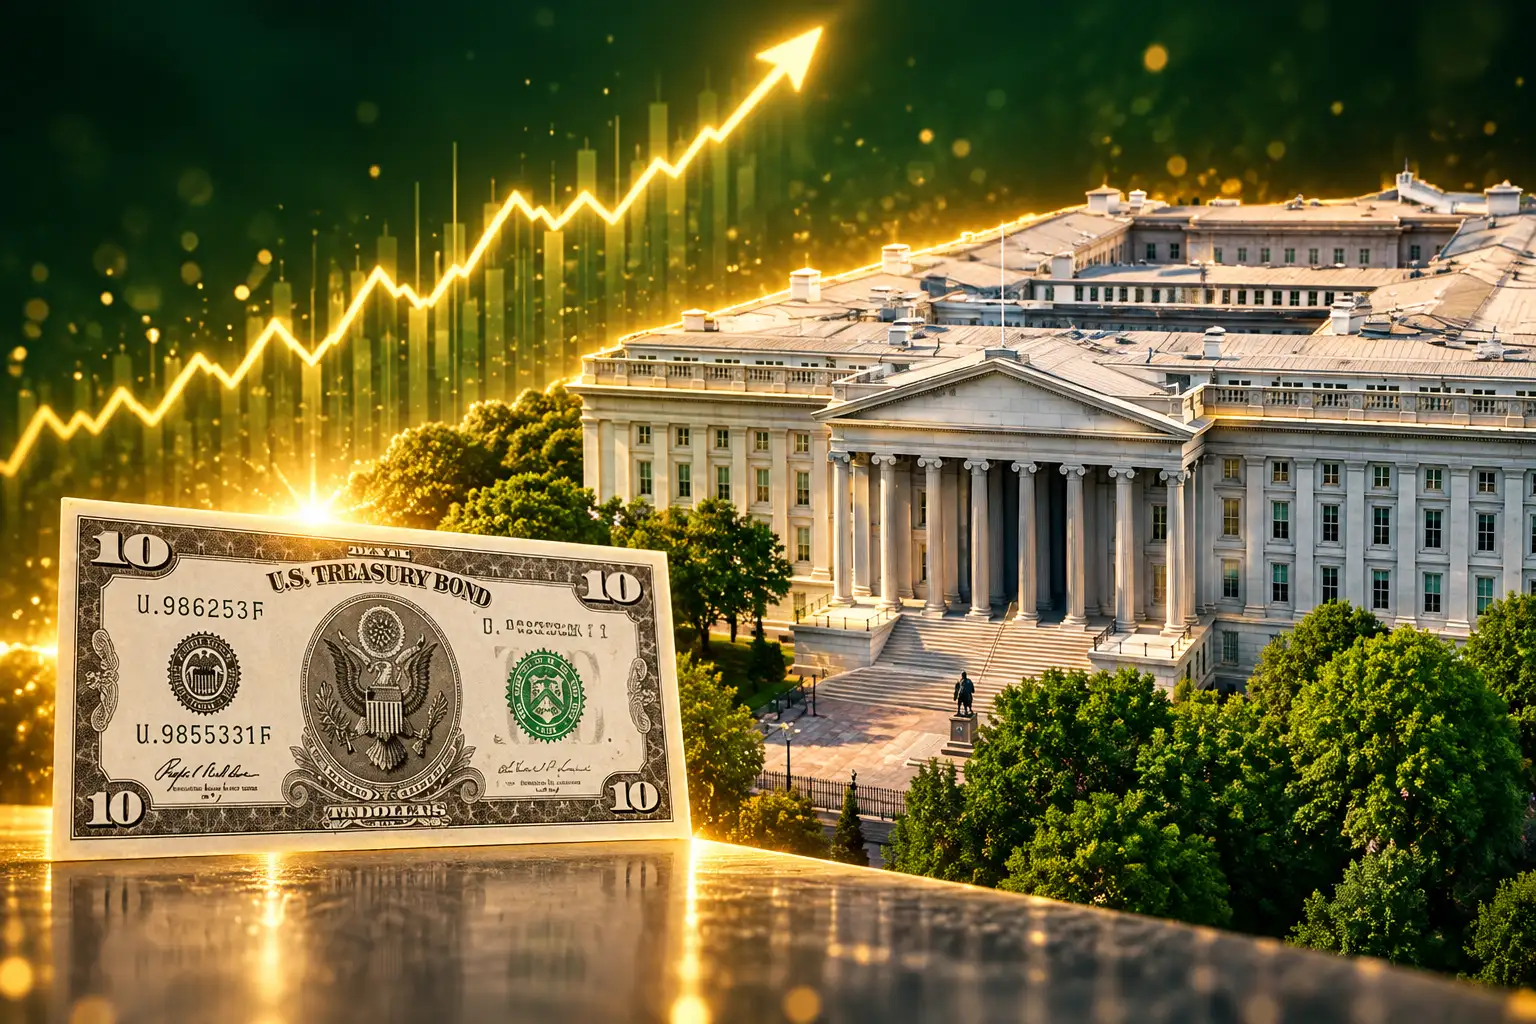
U.S. 10-year yields hit 5.36%, a 24-year high, even as a $39 billion auction cleared, with AI borrowers now competing for the same long-term buyers.

The U.S. 10-year Treasury yield touched 5.36% on October 7, its highest level since 2002, before a $39 billion auction pulled it back. The 30-year yield hit 5.73%, also the highest since 2002. Governments are paying those rates with oil still above $100 a barrel, and AI companies are now raising tens of billions in the same long-dated market.
By early October 8 the 10-year was back near 5.31% in Asian hours. The next test is a $22 billion sale of 30-year bonds scheduled the same day.
The $39 Billion Note Sale Stopped Through
Investors had spent the morning treating the 10-year sale as a risk event. The note’s yield had already printed 5.36%, and a weak book would have pushed long rates higher still. The $39 billion 10-year sale stopped at 5.300%, 1.7 basis points through the 5.317% when-issued yield, so the Treasury paid less than the screen had been implying.
That 5.300% stop was still the highest yield at any U.S. 10-year auction since November 2000, when the high yield was 5.865%. Demand gauges did not look like a buyers’ strike. The bid-to-cover ratio was 2.77, against a six-month average of 2.54. Indirect bidders, a group that includes foreign accounts, took 80.3% of the competitive award after averaging 74.1% over six months. Primary dealers were left with 2.5%, against a twelve-month average of 9.44%.
HOW THE 10-YEAR AUCTION CLEARED
| Gauge | October 7 result | Comparison |
|---|---|---|
| High yield | 5.300% | Highest since November 2000 (5.865%) |
| Bid-to-cover | 2.77 | 2.54 six-month average |
| Indirect bidders | 80.3% | 74.1% six-month average |
| Direct bidders | 17.1% | Rest of the competitive book |
| Primary dealers | 2.5% | 9.44% twelve-month average |
After the results, the on-the-run 10-year eased to 5.27%, 9 basis points below the session high. Peter Boockvar, chief investment officer at One Point BFG Wealth Partners, put the bounce down to the level itself.
Bottom line, for whatever reason, likely the 24 yr highs in rates, brought out the buyers and resulted in a great auction.
Peter Boockvar, chief investment officer, One Point BFG Wealth Partners
That is the split the tape supports. The United States can still place 10-year debt. The price of that bid is the highest auction yield since 2000, and foreign accounts took most of the paper. A 5.3% 10-year is a clearing yield, not a failed one, and it is also a coupon governments now have to live with on new long-term borrowing.
AI Borrowers Join the Queue for Long Money
The same session that tested Treasury demand was filled with reports that private AI borrowers are lining up behind governments. SpaceX is reported to be raising about $40 billion to buy Nvidia chips, roughly $10 billion of bank loans and $30 billion of investment-grade debt, with a close talked about for 2027. The company already sold $25 billion of bonds in June. Its total debt was $38.4 billion as of June 30, up from $22 billion at the end of 2025, and those June bonds carried coupons from 5.35% to 6.65%, a weighted average of 5.855%.
That check is still a plan, not a completed sale. The money already raised around it is not. Neuberger Berman put hyperscaler, data-center and semiconductor financing at about $165 billion before mid-2026, some $27 billion more than the whole of 2025. European Central Bank market staff wrote in August that hyperscalers are projected to need more than $1 trillion of capital spending by 2028, equal to 3% of current annual U.S. GDP, and that U.S. demand for long-dated funding has already fed the rise in long-term real yields.
Europe is writing a growing share of those checks. Huw van Steenis, an economic strategist at Apollo, wrote on October 7 that hyperscalers have raised $48 billion in European-currency bonds this year as of September 25, more than triple the entire amount of 2025.
WHERE THE $48 BILLION WAS RAISED
- Euro notes: €27 billion, or 3% of euro investment-grade issuance this year.
- Sterling notes: £13 billion, or 10% of sterling investment-grade issuance.
- Swiss franc notes: CHF 7.5 billion, or 22% of Swiss franc investment-grade issuance.
- U.S. comparison: hyperscalers are 8% of U.S. investment-grade corporate issuance, and 7% of euro deals with maturities of 10 years or more.
Apollo’s own note says there are few signs of crowding out yet. Non-hyperscaler investment-grade sales are little changed from a year earlier, and corporate spreads remain tight. The ECB blog reached a similar first-wave verdict for euro companies: cover ratios for European issuers stayed strong, even as some of them timed deals to avoid days when the U.S. names were in the market. Hyperscalers still accounted for 15% of the increase in domestic euro corporate bond holdings in the year to March 2026, with pension funds and insurers buying the long paper.
WHERE EXPERTS DISAGREE
- Huw van Steenis, Apollo: hyperscaler supply is adding highly rated U.S. names to European credit indexes, and crowding out is not showing up in other issuers’ books yet, though financing is forecast to rise a further 25% in 2027.
- ECB market staff: euro-area companies have not lost access so far, but AI demand for long-dated funding has already contributed to higher long-term real yields in the United States, with possible later spillover into sovereign paper if the investor pie does not grow.
- Ed Yardeni, Yardeni Research: the sharper sovereign stress is France, whose 10-year yield has risen more this year than any other major economy, with the United States second and Italy third.
The second-order pressure is the duration. Hyperscalers are selling 10-year-plus bonds into a market where some governments, including the United Kingdom, have been shortening the debt they issue. Every extra dollar of long AI paper is a bid for the same scarce pool of pension and insurer money that also has to absorb Treasurys, gilts and OATs.
France Is the Sharper Sovereign Stress
The U.S. 10-year made the headlines because it is the world’s benchmark. The worse price action on October 7 sat in Europe. British 30-year gilt yields jumped 13 basis points to a peak of 6.036%, the highest since January 1998. The UK 10-year yield rose to 5.48%, just short of its highest level since 2007. Early on October 8 the 30-year gilt was nearer 5.98%, off that peak and still historically expensive.
France remains the country the credit market is treating as the problem child. The spread between French and German 10-year yields widened about 11 basis points on October 7 to 140 basis points, after touching almost 160 basis points the previous week, a gap last seen in the 2012 crisis years. Italy’s 10-year gap over Germany had already widened to 130 basis points last week from 80 basis points a month earlier. Ed Yardeni wrote that France may be on the verge of a full-blown debt crisis, ranking its 10-year move this year ahead of the United States and Italy.
Robin Brooks, a senior fellow at the Brookings Institution, put France as the shock’s epicenter, with Italy, the UK and Spain also under pressure and Swiss paper catching the safe-haven bid. Replies to that post pointed out that U.S. yields were being hit at the same time, and that flows into Treasurys as a haven are being used to explain both rallies and selloffs. The U.S. still sold its 10-year. France is the name whose spread over Germany keeps setting the tone for the rest of the euro market.
LONG YIELDS ON OCTOBER 7
| Bond | Intraday high | Last time that high |
|---|---|---|
| U.S. 10-year | 5.36% | 2002 |
| U.S. 30-year | 5.73% | 2002 |
| UK 30-year gilt | 6.036% | January 1998 |
| UK 10-year gilt | 5.48% | Near the 2007 high |
John Healey, the UK finance minister, faces his first budget on October 28. Thirty-year gilts used to be a large part of Britain’s issuance, so a 6% long rate is not a screen curiosity for the debt office. It is the cost of the long end of the book.
Georgieva Tells Governments the Easy Ride Is Over
Overnight into the U.S. session, IMF Managing Director Kristalina Georgieva used a curtain-raiser speech in Singapore to tell finance ministers the same thing the bond market was already pricing. Public debt is at its highest since World War II and on course to exceed 100% of global GDP before 2030. Advanced economies, she said, are the worst offenders. The IMF’s 191 members meet in Bangkok from October 12 to October 18.
She named three crosscurrents: the AI boom, persistently high energy prices, and record public debt. In her telling the world is being pulled by a negative energy supply shock and a positive demand shock from AI, and the mix is inflationary. Brent was still above $100 a barrel on October 7, down 0.5% on the day, and near $102.37 early on October 8. She said diesel and other refined products have been pushed to record levels by a shortage of refining capacity, and that Brent futures imply high oil prices through 2027.
Policymakers had a relatively easy ride over the last 17 years, as for all that time interest rates were stuck below GDP growth rates. Higher interest rates now put an end to that.
Kristalina Georgieva, managing director, IMF curtain-raiser, Singapore
The line that matters for a 5.36% 10-year is the arithmetic she laid out after that. Elevated yields inflate the interest bill while defence and other claims compete for the same budget, and higher policy rates then lift the short end of the debt that rolls over every year. She called recent rate increases by the Federal Reserve, the European Central Bank and the Bank of Japan “highly appropriate,” and said this may be a time for a prudently hawkish bias. She also said governments cannot wait for growth alone to shrink the debt, and that interest rates stuck below growth for 17 years will not return as a free lunch.
The global economy is navigating 3 powerful crosscurrents: AI, high energy prices, and record public debt. In my curtain-raiser speech in Singapore, I set out what’s at stake as we gather for the #IMFMeetings in Bangkok next week and why action can’t wait. https://t.co/YVPLgYHI1U pic.twitter.com/itBc1Y5tu4
— Kristalina Georgieva (@KGeorgieva) October 7, 2026
Georgieva’s speech treats AI as both the growth hope and another inflation shock, because the build-out bids for power, chips and, now, long-term credit. That is the link the Treasury tape is starting to show. The companies building the data centers are not waiting for governments to finish their own sales.
The Russell 2000 Dropped 1.3%
Equity markets had set records on October 6. They gave some of that back once the 10-year printed 5.36%. The S&P 500 and the Nasdaq ended October 7 down about 0.2%. The Dow fell 341 points, or 0.6%. The Russell 2000, which tracks small and midsize companies, declined 1.3%.
HOW THE SESSION SPLIT
- U.S. large caps: S&P 500 and Nasdaq down about 0.2% after record closes the previous day.
- U.S. small caps: Russell 2000 down 1.3%, the cleaner read on higher long rates.
- Europe: Stoxx 600 down 1%, France and Germany around 1.3%, Italy’s FTSE MIB down 2.5%.
- Oil: Brent down 0.5% on October 7 and still above $100 a barrel, near $102.37 early on October 8.
Smaller U.S. firms fund more of their growth in the credit market and less from cash on the balance sheet, so a 5.3% 10-year hits them faster than it hits the mega-cap names that have been selling the AI bonds. The 10-year is also the reference rate for 30-year fixed mortgages. Households do not bid at the 1 p.m. auction; they meet the same yield in the rate on a home loan, a car loan, and the discount rate on the stock market.
The 2-year yield, which tracks the policy path more closely than the long end, was down 2.3 basis points at 4.768% in afternoon trading on October 7. Minutes from the Fed’s latest meeting still showed most officials seeing another possible rate increase by year-end. The curve’s message was not a sudden repricing of cuts. It was a higher term premium on long debt, which is the part AI issuers and finance ministries now share.
Thursday’s $22 Billion Long Bond
Wednesday’s 10-year was the middle sale of a three-day coupon run. The long bond is the one that has to clear closest to that 5.73% high.
THIS WEEK’S COUPON SALES
- October 6, 2026: Treasury sells $58 billion of 3-year notes at a high yield of 4.932%.
- October 7, 2026: Treasury sells $39 billion of 10-year notes at 5.300%, 1.7 basis points through the when-issued yield, with indirect bidders taking 80.3%.
- October 8, 2026: Treasury is scheduled to sell $22 billion of 30-year bonds, a reopening of the 5.125% bond due August 15, 2056, with competitive bids due at 1:00 p.m. Eastern.
The previous 30-year reopening, on September 10, stopped at 5.308% with a bid-to-cover of 2.61 and indirects at 79.5%. The market yield on October 7 went as high as 5.73% before pulling back. A $22 billion long-bond sale at those levels asks the same foreign accounts that just took 80.3% of the 10-year to extend further out the curve, on a day when 30-year gilts have already printed 6.036% and hyperscalers are still in the queue for 2027.
The 10-year sale showed that 5.3% is a yield at which the book gets filled. It did not show that governments can go back to borrowing as if the 17-year stretch of cheap money were still running. AI issuers will keep selling long paper because the build-out is too large to fund from cash. Finance ministries will keep rolling debt because the interest bill is already rising. Both will be in the same line on October 8.
Disclaimer: This article is news reporting and analysis of bond-market moves, government sales and company financing plans, and it is for information only. It is not investment advice, a recommendation to buy or sell Treasurys, gilts, corporate bonds or shares, or a forecast of auction results or interest rates. Readers who are considering bond purchases, mortgage decisions or portfolio changes should consult a licensed financial adviser or investment professional who can look at their own circumstances. Yields, auction sizes, debt totals and company fundraising plans reflect the sources cited as of the dates named in the piece and can change with the next sale or filing.

Clay Moulds From the Blyth Hoard Fit Peebles Fittings

Treasury Yields Hit a 24-Year High as AI Joins the Queue

Crew-12 Leaves the ISS With Fedyaev and Adenot Aboard

The Graziers Recall Puts the 60-Day Cheese Rule on Trial

Hugo Chavez’s Hollywood Welcome Meets a Film About Escape

Sons of Behemat Add a Witch and a Middle Rank

Canada Still Clears Mazatlán as the Cartel War Arrives

The FTC Suit That Targets Amazon’s Hidden Ad Floor

Samsung Leads Mistral’s Record European Sovereignty Round

Women, Gym, and Affairs: A Complex Intersection
-
 GAMING1 month ago
Sons of Behemat Add a Witch and a Middle Rank
-
 NEWS2 years ago
Canada Still Clears Mazatlán as the Cartel War Arrives
-
 BUSINESS1 month ago
The FTC Suit That Targets Amazon’s Hidden Ad Floor
-
 NEWS1 month ago
Samsung Leads Mistral’s Record European Sovereignty Round
-
 LIFESTYLE2 years ago
Women, Gym, and Affairs: A Complex Intersection
-
 AUTO2 years ago
Laepple Automotive Bets on a Vacant Detroit Die Shop
-
 AUTO2 years ago
Tamil Nadu Auto Keeps Growing Inside a Climate Red Zone
-
 LIFESTYLE2 years ago
The Unstoppable Rise of Hot Honey: Are Food Trends Making UK Restaurant Menus All the Same?